Menu Bar

Home           Calendar           Topics          Just Charlestown          About Us
Showing posts with label insurance. Show all posts

Saturday, September 26, 2026

Study links soaring health care spending to higher insurance premiums

Stating the obvious

By Mike Cummings, Yale University

Edited by Sadie Harley, reviewed by Andrew Zinin

Growth in health care spending in the United States is driving increases in health insurance premiums, limiting people's access to care and contributing to wage reductions, job losses and rising inequality, according to a new study co-authored by Yale economist Zack Cooper.

The study—an analysis of state-level data on insurance premiums, health spending and insurer markups from 2011 to 2024—found that rising spending accounted for 91% of the growth in premiums during the period covered.

The finding suggests that measures to slow increases in health insurance premiums should focus on reining in the growth of health care spending, said Cooper, who directs the Health Care Affordability Lab at Yale.

"Insurance premiums are rising rapidly, putting an immense amount of pressure on people across the country," said Cooper, an associate professor of health policy at the Yale School of Public Health and of economics in Yale's Faculty of Arts and Sciences.

"Our work shows that growth in premiums is being driven by growth in health care spending. This means that efforts to address the high cost of insurance premiums require thinking about how to make health care spending more affordable."

The study was published in the journal JAMA Health Forum. Stuart V. Craig of the University of Wisconsin-Madison is the study's co-author.

Thursday, September 24, 2026

Medicare Costs Are Rising in 2027

Here’s What Seniors Need to Know

By Terry H. Schwadron

Seniors face higher drug costs, shrinking Medicare Advantage benefits and growing pressure to pay more for their health care in 2027.

It seems all but definite that Medicare, federally paid medical insurance for seniors, will cost more next year.

While there still are some loose ends around the rules, there is no question that providers of Medicare Advantage plans are cutting back on current benefits, that general monthly premiums are going up and that prescription drug caps are being significantly changed or dropped altogether.

Like health care offered more widely through the Affordable Care Act and through Medicaid cuts to those eligible by income and disability, the government is about to execute its broadest and deepest cuts to health insurance for seniors as well. Obviously, seniors have more medical issues than younger Americans.

Donald Trump has said on multiple occasions that he wants to protect seniors from cuts hitting other parts of the overall health system, though he is happily having Vice President JD Vance looking for fraud in billing and service claims. But reports from providers, retirement advocates like AARP and political sources say otherwise.

And, if you go to Medicare.org to learn just how it will affect you, good luck. They are not addressing the issues. We are on the cusp of annual open medical enrollment starting Oct. 15 and the details of health care do not seem to be among the top agenda items for our elections.

Indeed, despite a series of self-serving statements about cutting the price of a select number of prescription drugs, Trump has variously insisted that states should fund Medicare and Medicaid or somehow privatize payments.

Trump said in April that it’s “not possible” for the federal government to fund Medicare, Medicaid and childcare costs, arguing that it should be up to the states to “take care” of those programs while the federal government focuses on military spending.

Wednesday, September 23, 2026

Trump and Kennedy’s Health Industry Deals Haven’t Been Enforced and Are at Risk of Vanishing

No surprise, given who's in charge

In the thick of his competitive reelection race in Michigan, Republican Rep. Tom Barrett joined Health and Human Services Secretary Robert F. Kennedy Jr. at a sprawling 400-acre apple orchard, farm, and winery. They touted Trump administration efforts to improve the American diet, including the removal of some artificial dyes from processed foods.

“We had a great discussion about healthy options for all Americans and taking back control of our healthcare,” Barrett said in a June Instagram post, after sampling the farm’s apple cider.

Like the focus on artificial dyes, however, many of the administration’s highest-profile health initiatives rely on voluntary agreements. The goals, such as lower drug prices and nutrition classes for doctors, have widespread appeal, cutting across party lines and economic divisions.

But the administration-industry deals lack the enforcement teeth of more traditional federal regulation. Their details are vague, and minimal oversight makes it hard to monitor progress. In some cases, the administration has claimed victories that have yet to materialize.

Republicans consider the dealmaking a winning strategy. It fits with the party’s anti-regulatory stance, they say, and enables the administration to quickly forge agreements Donald Trump and his allies can tout as accomplishments. In the run-up to the midterm elections, some, like Barrett, hope to woo voters by trumpeting the Trump administration’s efforts to shape health policy.

Thursday, September 17, 2026

Trump’s $500 Healthcare Rebate Plan Called ‘An Absolute Joke’ as Premiums Skyrocket

But of course, Trump NEVER pays

Jake Johnson for Common Dreams

Donald Trump said that his administration would issue $500 rebate checks to some Americans who were purportedly “overcharged” under the Affordable Care Act, a move that would provide little to no relief to the millions of people impacted by surging health insurance premiums.

The White House said in a fact sheet that around a million Americans in 30 states would receive rebate checks, beginning next month—just weeks before the November midterms. 

Brad Woodhouse, president of the advocacy group Protect Our Care, ripped the rebate plan as “an absolute joke,” calling $500 “a drop in the bucket compared to what Americans are paying because Trump and Republicans gutted healthcare to bankroll massive tax breaks for billionaires and big corporations.”

Woodhouse was referring to a Republican budget measure, signed into law last summer by Trump, that enacted more than $800 billion in cuts to Medicaid over the next decade.

The GOP also declined last year to extend enhanced ACA subsidies that helped reduce costs for tens of millions of Americans, sending premiums skyrocketing. Some families have seen annual premium increases in the thousands of dollars, leading many to drop marketplace coverage entirely. ACA premiums are set to surge by double digits for a second consecutive year in 2027.

Sunday, September 13, 2026

The greenest building is the one still standing after a disaster

Build green for lower costs and survival

Fernanda Cruz Rios, Drexel University

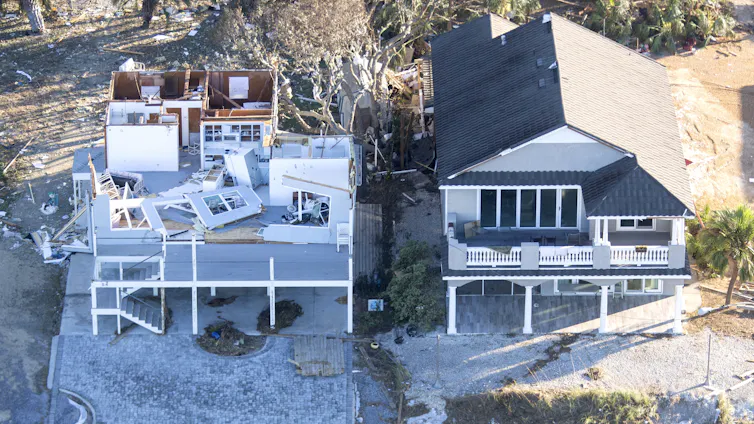
Two homes side by side, one mostly untouched, the other largely destroyed, with walls torn out and the roof gone.
Construction choices are often the difference between a house surviving a hurricane or being torn apart. Mark Wallheiser/Getty Images

When Hurricane Michael tore through the Florida Panhandle in 2018, a beach house called the Sand Palace was left standing, while more than half the buildings around it were destroyed.

Its owners had built it to withstand roughly double the wind speed that Florida’s code required, with reinforced concrete walls on 40-foot (12-meter) pilings. The cost was about 15% to 20% more than standard construction, but the owners wanted a house that could survive storms.

The owners of the Sand Palace talk with WJXT4 about why they built the home to survive hurricanes.

Designers usually measure how “green” a building is by its carbon footprint – the greenhouse gases released making, transporting and running everything that goes into it. The Sand Palace’s extra concrete expanded its carbon footprint, making the house appear less environmentally friendly on paper.

But a green building has to last for its intentionally small carbon footprint to make a positive difference. Damage from a flood, a wildfire or a hurricane can require significantly more building materials to repair it, ballooning its carbon footprint over time.

As storms happen more often and with more intensity, considering the full life cycle of a building and its costs over time becomes increasingly important to get an accurate picture of how sustainable that building really is.

Thursday, September 3, 2026

‘Utterly Unsustainable’: Employer-Sponsored Healthcare Costs Set to Keep Surging

Bad choices no matter where you look

Brett Wilkins for Common Dreams

US workers with employer-sponsored health insurance are expected to spend an average of $5,297 on healthcare this year, including premiums deducted from their paychecks, deductibles, and copayments, according to a new estimate from benefits consulting giant Aon reported Thursday by The Wall Street Journal.

That’s $388 more than last year, and the pain is expected to intensify in 2027. According to a survey conducted by WTW, another consultant, US employers anticipate their healthcare costs will soar 11.1% next year. That could be the steepest increase in more than two decades, and would mark the fifth consecutive year of rising employer healthcare costs.

As the Journal noted, expensive cancer treatments and widespread adoption of weight loss drugs are among the factors driving up spending—and costs. For workers, that means larger deductions from their paychecks, higher out-of-pocket costs, and, for some, abandoning insurance altogether.

“Employers are telling us that this is utterly unsustainable,” WTW population health leader Jeff Levin-Scherz told the Journal.

Wednesday, September 2, 2026

Nearly one in five Medicaid-eligible adults may miss new 80-hour work rule

Trump covering health coverage for more people

By Boston University

Edited by Gaby Clark, reviewed by Robert Egan


Map of the Proportion of Adults Age 18 to 64 Years at Risk of Noncompliance Who Were Plausible Medicaid Expansion Enrollees and Potentially Subject to Work-Reporting Requirements, by State. Credit: JAMA Health Forum (2026). DOI: 10.1001/jamahealthforum.2026.2938

A new study found that nearly 20% of eligible adults in Medicaid expansion states are in danger of not meeting the minimum work hours that will be required nationwide beginning Jan. 1. Women, unmarried people, white individuals and those with limited education all had a higher risk of losing their health coverage due to noncompliance with these new requirements.

Up to 10 million people may lose Medicaid coverage in the United States due in part to new work requirements and eligibility redeterminations under the One Big Beautiful Bill Act (OBBBA), which mandates a reduction of nearly $1 trillion in Medicaid spending over a decade.

While the administrative burden associated with meeting and maintaining these work requirements is expected to be the primary driver of disenrollment, a new study led by researchers at Boston University School of Public Health (BUSPH) and the Arnold School of Public Health at the University of South Carolina (Arnold School) found that millions of Medicaid enrollees may lose their health coverage because they are unable to achieve the required work hours.

Who is most at risk

Set to take effect nationwide on Jan. 1, 2027, the new federal Medicaid work reporting rules require adults enrolled in the Affordable Care Act's Medicaid expansion to show that they are working, volunteering, enrolled in school and/or participating in job training for at least 80 hours per month, with certain groups exempt. But the new study found that nearly 20% of Medicaid-eligible adults living in states that expanded Medicaid are at risk of noncompliance because they are unlikely to fulfill the minimum required hours once the rules take effect. The findings are published in JAMA Health Forum.

Certain groups were more at risk of noncompliance than others. Women had a 22% higher probability of having insufficient or inconsistent work hours than men, while married Medicaid enrollees had an 18% lower probability of noncompliance than unmarried enrollees.

Sunday, August 30, 2026

Neronha urges state regulators to reject proposed health insurance premium hikes

The cost of health insurance is too damn high

By Alexander Castro, Rhode Island Current

Rhode Island Attorney General Peter Neronha is urging state regulators to reject two insurers’ proposed increases to premiums for individual health plans in 2027.

After a July administrative hearing by the state’s Office of the Health Insurance Commissioner (OHIC), Neronha’s office formally submitted a brief objecting to Neighborhood Health Plan of Rhode Island’s (NHP) request for a rate increase of 22.4%.

Premium increase requests are submitted annually by insurers, and this year they were submitted to the commissioner’s office on May 18. The agency then reviews the submissions and can accept, modify or reject them, with the final approved rates expected to arrive in September. Rate hike requests trigger a formal, public, administrative hearing if they exceed 10%.

So the health insurance commissioner’s office held a hearing for Neighborhood Health Plan but not for Blue Cross Blue Shield of Rhode Island, which requested a 9.8% increase. The AG instead submitted public comments encouraging the office to reject Blue Cross Blue Shield’s proposed rates.

Collectively, the two insurers cover more than 50,000 Rhode Islanders who purchase their individual plans through the state’s health insurance marketplace.

Friday, August 21, 2026

Will flu, COVID-19 vaccines be available this fall?

What road blocks will Bobby Jr. and Trump throw up?

Meghan Holohan

As fall nears and the respiratory illness season begins, many people are wondering if they’ll be able to receive updated flu and COVID-19 vaccines amid the turmoil created by the federal government about vaccines. Some worry that recent changes could mean they have to pay out of pocket for their annual doses. 

But experts say Americans don’t have to worry about vaccine coverage—this year, at least. 

“There will be available an updated influenza vaccine and an updated COVID vaccine. So far, that’s pretty normal,” William Schaffner, MD, professor of infectious diseases at Vanderbilt Health and spokesperson for the Infectious Diseases Society of America (IDSA), told CIDRAP News. “Insurers, that is, the medical insurance industry, have said that they would cover those vaccines.” 

Saturday, August 1, 2026

Celebrate Medicare and Medicaid—and Protect Them From Trump!

Trump and his allies in Congress apply "Death of a Thousand Cuts"

Max Richtman in Common Dreams

There is reason to celebrate Medicare and Medicaid turning 61 years old. Both highly successful programs were signed into law by President Lyndon B. Johnson on July 30, 1965 as a cornerstone of his Great Society agenda. But this year, our celebration is tempered by grave concern over the future of both programs under the Trump regime.

Let’s compare the words of the two presidents:

LBJ:

No longer will older Americans be denied the healing miracle of modern medicine. No longer will illness crush and destroy the savings that they have so carefully put away over a lifetime. No longer will young families see their own incomes, and their own hopes, eaten away simply because they are carrying out their deep moral obligations to their parents.

Donald Trump:

It’s not possible for us to take care of… Medicaid, Medicare, all these individual things. They can do it on a state basis. You can’t do it on a federal. We have to take care of one thing: military protection. We have to guard the country.

The comparison speaks volumes. One is a leader who understood that the federal government has a crucial role in the protecting the health and well-being of our most vulnerable citizens—including the poor, disabled, and the elderly. The other is a president who claims to support Medicare and then says that the federal government can’t afford it because of his illegal war in Iran. So much for supporting Medicare.

But this goes deeper than Trump’s rhetoric. The Medicare program, like Social Security, is at a pivotal point in its history. The Part A hospital) trust fund must be fortified so that it doesn’t run dry in the 2030s. (There are reasonable solutions that Congress could enact without hurting seniors.) So far, though, we have heard no constructive ideas from Trump.

More urgently, though, the Trump administration is actively undermining the “traditional Medicare” program that LBJ signed into law. The administration has begun a pilot program to use AI bots to determine whether traditional Medicare patients will be covered for procedures their doctors have ordered. This appears to be an attempt to cut costs by erecting obstacles to medically necessary care—with decisions made by bots instead of human beings.

Sunday, July 26, 2026

MAGA declaring war on seniors — and it could be their downfall

Is Trump testing to see how much he can take away from seniors before they rebel?

Alex Henderson

According to data from the Roper Center at Cornell University, 50 percent of U.S. seniors — those who are 65 or older — voted for Donald Trump in 2024 compared to 49 percent for Democratic presidential nominee Kamala Harris. 

The senior vote was close in 2024, and seniors, Roper says, played an important role in getting Trump past the finish line. But according to Salon's Heather Digby Parton, seniors could be the ones who doom Republicans in the 2026 midterms.

Parton notes that because so many seniors vote GOP, "it's always been a mystery" to her "why Republicans have always been so bent on destroying the safety net that brought the elderly out of poverty and assured them a baseline level of subsistence and medical care." And she points that crucial safety-net programs used by seniors — Social Security and Medicare — came from liberal Democratic presidents.

"From the moment Franklin D. Roosevelt signed the Social Security Act in 1935 to the day Lyndon B. Johnson signed the Medicare and Medicaid Act 30 years later," Parton explains, "the right has been trying to destroy them. In the early days, it sprang from their obsession with anti-communism, arguments that the country couldn't afford it, and that individuals and their families are rightfully responsible for their own care in old age.

“In a 1961 radio address — 20 years before he became president — Ronald Reagan said, 'One of the traditional methods of imposing statism or socialism on a people has been by way of medicine' ... Before Medicare was created, only 54 percent of elderly people had health insurance, and that could be cancelled without cause when they got sick — which, as you know, tends to happen when you get old."

Parton continues, "Three years after it was enacted, 96 percent of people over 65 had hospital insurance. It was literally a life saver. Over the years, Medicaid, created at the same time to assist people living below the poverty line, came to cover many of the health expenses that Medicare didn't for elderly people, most importantly for nursing homes and caregivers. The GOP has been hacking away at these vital programs ever since, and yet, senior citizens have been voting for them in greater numbers than any other age cohort."

Thursday, July 23, 2026

Rhode Island needs this!

A New Option for Long-Term Care Costs

Kelly Haggett figures that a mandatory surcharge added to Washington state’s payroll tax cost her about $500 last year. But she doesn’t really mind.

“On a scale of 1 to 10 of my annoyance with taxes in general, this one is about a 2,” she said. “I see the benefits.”

The small surcharge on wages provides the funding for Washington Cares, the nation’s first state-operated program for long-term care insurance. It was set to begin distributing benefits July 1.

If Haggett, 67, a systems administrator who lives in Auburn, Washington, needs help with daily activities as she ages — bathing, dressing, grocery shopping, managing medications — she’ll be able to use the benefit she has accrued through WA Cares, as the program is known.

About 3.7 million workers participated last year, paying an additional 0.58% in payroll taxes. Those who contribute for 10 years will qualify for a lifetime benefit of $36,500. The amount will rise with inflation: A 36-year-old now earning about $50,000 a year who contributes $291 a year for a decade will have a projected $98,000 benefit if she needs assistance at age 75.

Both the WA Cares mandatory premiums and eventual benefits are modest. But for older adults and people with disabilities, they can help pay for a variety of services: home care, transportation, adult day programs, home modifications like ramps and grab bars, compensation for family members who assist them, or assisted living facilities and nursing homes.

Haggett had looked into private long-term care insurance to cover those needs, but she balked. “It’s crazy expensive,” she said. And since premiums can rise, and frequently have, “you’re basically saying, I’ll pay whatever, whenever.”

Tuesday, June 30, 2026

New Trump plan would put healthcare decisions in the hands of Trump political appointees

Politics Should Never Decide Who Gets Care

Teri Mills and Donna A. Gaffney for Common Dreams   

As a nurse educator and a psychiatric-mental health nurse, we have built our careers on evidence-based practice, ethics, and compassion when caring for patients. Politics never entered the picture. Our responsibility has always been to provide care guided by science, professional standards, and the individual needs of our patients, not political ideology or partisan priorities. That is why the Office of Management and Budget’s proposed rule, Docket OMB-2026-0034, which would hand healthcare funding decisions to political appointees, stops us cold.

At first glance, this proposal may sound administrative or technical. In reality, it would fundamentally alter how federally funded healthcare, nursing education, behavioral health programs, and scientific research are approved, monitored, and terminated. Under rule §200.340, any grant can be ended at any point if it no longer aligns with the priorities of the administration. That is not oversight. It is political control.

For nurses, the consequences would not be abstract. They would be immediate, personal, and dangerous for the patients we care for.

Friday, June 19, 2026

Trump issues rules for sick people on Medicaid

"Throw down your crutches and go pick cotton"

The Trump administration has issued final rules on how states should ensure that millions of Medicaid enrollees prove they’re working or completing other activities, such as job training, volunteering, or being enrolled in an educational program.

The Centers for Medicare & Medicaid Services released the rules on June 1. That deadline was set last year in the GOP tax-and-spending law known as the One Big Beautiful Bill Act, which established a work requirement for certain people enrolled in Medicaid, the state-federal health insurance program for people with low incomes or disabilities.

Medicaid agencies are scrambling to rework IT systems and make sure they have staff to effectively enforce the rules, while also keeping enrollees from losing coverage for administrative reasons, such as difficulty navigating state eligibility portals.

The newly announced regulations offer a clearer picture of what roughly 18.5 million Medicaid enrollees will have to do to prove they qualify for benefits.

Jim Torres, who helps people enroll in health coverage at the Samuel U. Rodgers Health Center in Kansas City, Missouri, said a “very small percentage” of his clients have heard of the changes coming to Medicaid.

Thursday, June 18, 2026

Sen. Victoria Gu gives her review on the recently ended General Assembly session

Highlights from a productive session 

By Victoria Gu

Dear Friends and Neighbors, 

We’ve finished another legislative session! After many nights of long committee hearings, bill sponsors and committee chairs work on their bill edits, and June is when bills can be approved for votes in committee and then gain final passage in the House & Senate. 

New Leadership: In the past month the RI House of Representatives also elevated Majority Leader Blazejewski to the position of House Speaker and Majority Whip Katie Kazarian to the position of House Whip. Congratulations to them and the outgoing Speaker Joseph Shekarchi for their years of service.

Bills I Passed

Shoreline Access Disclosure for Oceanfront Property Rentals:

The House & Senate passed my bill S-2734A to help make sure renters and short-term rental guests understand Rhode Island’s shoreline access rights.

Part of the motivation for this bill came from seeing some short-term rental listings advertise a “private beach,” even though Rhode Island law protects public shoreline access up to 10 feet above the recognizable high tide line. This bill helps make sure visitors and tenants get clear information about those rights before they stay at an oceanfront property. 

Food is Medicine: The General Assembly has passed my Food as Medicine bill, which creates a task force to design a Medicaid pilot program that uses medically tailored meals or other nutritional supports  to improve the health of patients with chronic, diet-related conditions. 

Food insecurity is strongly linked to many of the most costly preventable chronic diseases, including diabetes, cardiovascular disease, and obesity, which drive enormous health care spending. 

Medicaid accounts for about one-third of our state budget and is growing at an estimated 6% per year. Our budget will have a growing deficit unless we look at evidence-based programs like food as medicine.

60 Days Advance Notice of Home Insurance Non-Renewals: Insurance companies are being a lot more selective about the location and the condition of the houses they insure, declining to cover homes in coastal areas or with older roofs or water heaters. The bill that Rep. Azzinaro and I passed requiring 60 days’ advance notice will help homeowners find alternative insurance coverage and find tradespeople if they need to fix something at their house in order to continue insurance coverage.

Spotlight: Youth Mental Health

988 on Student & Staff Ids: Last week the General Assembly passed a bill Rep Earl Read & I sponsored to put suicide prevention and substance use crisis hotline numbers directly on student and school staff ID cards. At a time when young people are facing growing mental health challenges, we need to promote awareness of resources like 988.

The General Assembly also passed a youth crisis response service bill that codifies a successful pilot program into law. The program helps kids in crisis by getting them fast, specialized care with behavioral health clinicians (avoiding unnecessary emergency room visits) and connecting families to ongoing support.

Thank you to constituents who wrote to me about the importance of funding 988: This year, the Senate also advanced a separate bill by Senator Melissa Murray to protect the long-term funding of Rhode Island's 988 crisis line and BH Link services. More than 90% of 988 calls are resolved through phone support alone, connecting people with trained counselors before a crisis escalates. The bill stalled in the House, but we hope to pass it next year. More info here

Looking ahead: Vote for the Green Bond this Nov & Op-Ed on Managed Retreat

We got an extra $5 million for climate resiliency in the Green Bond which will be on the ballot in November! Annually, each town can apply for grants from this pool of funding to strengthen their infrastructure. One example: Westerly received funding for a flood wall around a pump station for the wastewater treatment plant. 

Managed Retreat: These photos I took in South Kingstown show how shoreline armoring—like rock walls and elevated structures—disrupt the dynamic beach ecosystem and make it harder for people to walk along the beach. As sea levels rise and more coastal property owners build hard structures to protect against erosion, the public part of the beach gets narrower, and in these pictures, it has become impossible to pass along the shoreline.

That's why we need to plan ahead before the next major storm. Instead of repeatedly rebuilding in areas that face increasing flood and erosion risks, towns can identify safer places for homes and infrastructure over the long term. Read more about our work to help Rhode Island communities prepare for rising seas and protect public access to our shoreline: 

https://www.providencejournal.com/story/opinion/columns/2026/04/18/rhode-islands-managed-retreat-plan-for-rising-seas-opinion/89628806007/

Budget Highlights

  • 62-65 year old early retirees will now get the same exemptions from Social Security tax as people 65 and older. Seniors still must have incomes under $107,000 for single filers and $133,750 for married filers in tax year 2025, to qualify.
  • Child Tax Credit - see this press release
  • Rural Health Transformation Grant - RI received over $150 million in the first year of this federal program and will use it to implement innovative programs like Community Paramedicine - see this website for more information. Stay tuned for more healthcare highlights and impacts of HR1 on our healthcare system

Senate Highlights

  • Labor Protections: We passed many noteworthy bills like S-2921

to give domestic workers the same protections under the Fair Employment Practices Act (FEPA) as other Rhode Island workers.

  • Immigration bills: see this press release and another for protecting constitutional rights
  • Education Funding Formula: only minor changes this year by increasing the “student success factor” - which is an additional amount of funding for each low-income student - from 40% to 43%. We will need to monitor the new Senate commission to study the funding formula, specifically the one suggested by the Blue Ribbon Commission
  • Status of CRMC reform bill: The bill that passed last year required the Governor to appoint members with expertise in coastal matters. There are some new members that the Senate confirmed this year with expertise with civil engineering, coastal wetlands, law, etc. but it remains to be seen whether the political dynamic will change and I still support the overall reform that would restructure CRMC so it’s similar to DEM, with a staff and director making the decisions instead of a politically appointed all-volunteer council.
  • Status of Bottle Deposit & Recycling bills: The bill that passed last year began the first stage which is a needs-assessment to look at our recycling system as a whole. That is still in progress

Federal flood insurance carries 2 moral hazards – which you face depends largely on how wealthy you are

The high costs of climate risk

Ivis García, Texas A&M University


Anyone who has been through a flood or hurricane knows the scene: waterlogged furniture piled on curbs, gutted homes with mold creeping up the walls, families displaced for months. But the recovery isn’t the same for everyone.

While federal flood insurance subsidizes risky coastal and waterfront development for wealthier homeowners by lowering the cost of living in these areas, many low-income households in flood-prone areas remain stuck with risky properties and little help.

As a disaster recovery researcher, I’ve witnessed how perverse incentives create different cycles of vulnerability across income levels. The problem with federal disaster insurance today isn’t just about subsidizing wealthier coastal homeowners – it’s equally about leaving low-income households systematically underinsured without resources to either protect themselves or leave.

Federal flood insurance’s moral hazards

The National Flood Insurance Program was established by Congress in 1968 to provide affordable flood insurance to the public while encouraging floodplain management.

Communities that participate in the program are required to adopt regulations to reduce flood risk in their areas for their residents to qualify. The insurance policies, around 4.7 million today, are purchased either through the program or insurance companies but administered and underwritten by the Federal Emergency Management Agency, the nation’s disaster response agency. When the policy cost is lower than the risk, the property is being subsidized by the federal program.

The National Flood Insurance Program did succeed in providing accessible insurance for many people, but it also produced a “moral hazard,” where people take on risk without bearing its full consequences. What’s less well understood is that this operates differently by income level.

FEMA is currently working to adjust flood insurance prices to more closely match each property’s actual risk. The program’s Risk Rating 2.0 changes, which began in 2021, aimed to transition policies to full-risk pricing for everyone. The annual premium increases are capped by law at 18% for primary residences, so full-risk pricing won’t be fully reached until around 2037, according to federal estimates.

But there’s another, less visible problem: Federal flood insurance already wasn’t affordable for many people.

In low-income neighborhoods, more than 90% of households are estimated to be underinsured, and their uninsured losses when they experience flooding often exceeds 20% of their annual income.

Many families are unable to afford federal flood insurance premiums – only 37% of all policyholders pay less than $1,000 per year, according to FEMA. Instead, homeowners may skip insurance, gambling that disasters won’t strike. When floods do occur, these households can face catastrophic uninsured losses.

Homeowners and renters may also choose federal flood insurance plans with lower premiums but that provide less coverage in a disaster, and even those plan costs can be high.

Because the federal flood insurance program doesn’t specifically help those who cannot afford premiums, this creates a structural trap: Wealthier homeowners receive government-subsidized insurance support for risky properties, while many lower-income households fall outside the system entirely.

EDITOR'S NOTE: Last year, Cathy and I received two homeowner insurance cancellations because of climate risk. A final carrier agreed to cover us on the condition we also buy federal flood insurance even though we are up on the tip of the moraine north of Route 1. That added an additional $1200 to the high premium charged by the new carrier.  - Will Collette

Saturday, June 13, 2026

Victoria Gu's homeowner insurance protection bill goes to Governor for signature

A modest aid to a growing, serious problem

The General Assembly approved legislation sponsored by Rep. Samuel A. Azzinaro and Sen. Victoria Gu to require insurers to provide customers with advance notice of nonrenewal for homeowners and residential fire insurance policies.

The legislation (2026-H 7066A, 2026-S 2011A) would require insurers to provide written notice of nonrenewal at least 60 days before the renewal date for homeowners and residential fire insurance policies, beginning July 1, 2027.

“Insurance companies are being a lot more selective about the location and the condition of the houses they insure, declining to cover homes in coastal areas or with older roofs or water heaters,” said Senator Gu (D-Dist. 38, Westerly, Charlestown, South Kingstown). “The 60 days’ advance notice will help homeowners find alternative insurance coverage and find tradespeople if they need to fix something at their house in order to continue insurance coverage.”

In recent years a number of insurers in Rhode Island have stopped providing home insurance, mirroring a national trend of higher prices and fewer options for homeowners.

The legislation now goes to the governor for his consideration.

EDITOR'S NOTE: Cathy and I had our homeowner policy cancelled TWICE last year due to increased risk from climate change. It was hard to find ANY carrier willing to replace our coverage. Having extra time to deal with such a mess is greatly appreciated  - Will Collette

Thursday, May 28, 2026

Retirees Are Worried About the Cost of Healthcare – and Who Can Blame Them?

Rising premiums, deductibles, co-pays, supplemental coverage and out of pocket costs hurt

Alicia H. Munnell 

The 10-percent increase in Medicare Part B premiums for 2026 has reignited concerns about how much Social Security and total income people will have after they cover their out-of-pocket (OOP) health spending.  Fortunately, my colleague Matt Rutledge has updated earlier research to answer precisely that question.

Even though retirees ages 65+ have Medicare, they still face considerable costs. In the case of Medicare Part A, which covers inpatient hospital care and is financed primarily by payroll taxes, beneficiaries face cost-sharing. Medicare Part B, which covers physician and outpatient hospital services, and Part D, which covers prescription drugs, are partly financed by premiums and include further cost-sharing. 

Because Medicare’s OOP costs are often substantial, many enrollees buy supplemental coverage, which may include additional premiums. Finally, many services, such as dental, vision, and hearing, are not covered by Medicare.

To identify total out-of-pocket healthcare costs, Matt used the 2018, 2020, and 2022 Health and Retirement Study (HRS). The sample included respondents who were ages 65+ and were receiving both Social Security and Medicare. In terms of expenditures, the HRS captures prescription drugs, special facilities, surgery, and medical visits to doctors, hospitals, and dentists. It also includes self-reported premiums paid for Medicare Part D, Medicare Advantage, and private supplemental plans. Medicare Part B income-related premiums were estimated based on the individual’s income. 

The central finding was the percentage of Social Security left after paying out-of-pocket health costs and how those results changed over the three surveys. As shown in Figure 1, the median percentage remaining in 2022 after medical OOP spending was 71 percent for Social Security benefits and 88 percent for total income. And these percentages were virtually unchanged over the three surveys.

In other words, OOP takes a big chuck of retirees’ resources, and the 10-percent increase in Medicare Part B premium suggests no relief on the horizon.

Wednesday, May 20, 2026

RI Senate passes Victoria Gu bill to require home insurers to give proper notice before cancellation

Climate change risk pushes insurers to cancel coastal home insurance 

The Senate approved legislation sponsored by Sen. Victoria Gu to require insurers to provide customers with advance notice of nonrenewal for homeowners and residential fire insurance policies.

“Insurance companies are being a lot more selective about the location and the condition of the houses they insure, declining to cover homes in coastal areas or with older roofs or water heaters,” said Senator Gu (D-Dist. 38, Westerly, Charlestown, South Kingstown). 

“The 60 days’ advance notice will help homeowners find alternative insurance coverage and find tradespeople if they need to fix something at their house in order to continue insurance coverage.”

EDITOR'S NOTE: Cathy and I went through this last year TWICE, each time finding insurance companies were changing the rules about covering properties near the coast. Once you find coverage, or maybe I should say IF you find coverage, prices are way up.  - Will Collette